Skip to content
Financing Institutions

Financing Infrastructure

Bring financing to every dealer and supplier in your network.

Paynion Financing Infrastructure is a ready-made platform that lets financing institutions extend credit through dealer and sub-dealer networks. From dealer hierarchies to supplier finance, from DBS to digital applications, every process goes live on existing infrastructure — no setup required.

Built for

  • Consumer finance companies
  • Leasing companies
  • Factoring companies
  • Banks
  • Manufacturers & distributors
Financing Infrastructure
Why it matters

The problems we solve

Financing never reaches the point of sale

Dealers sell without a simple way to offer or use financing, so deals stall or go elsewhere.

How we solve it

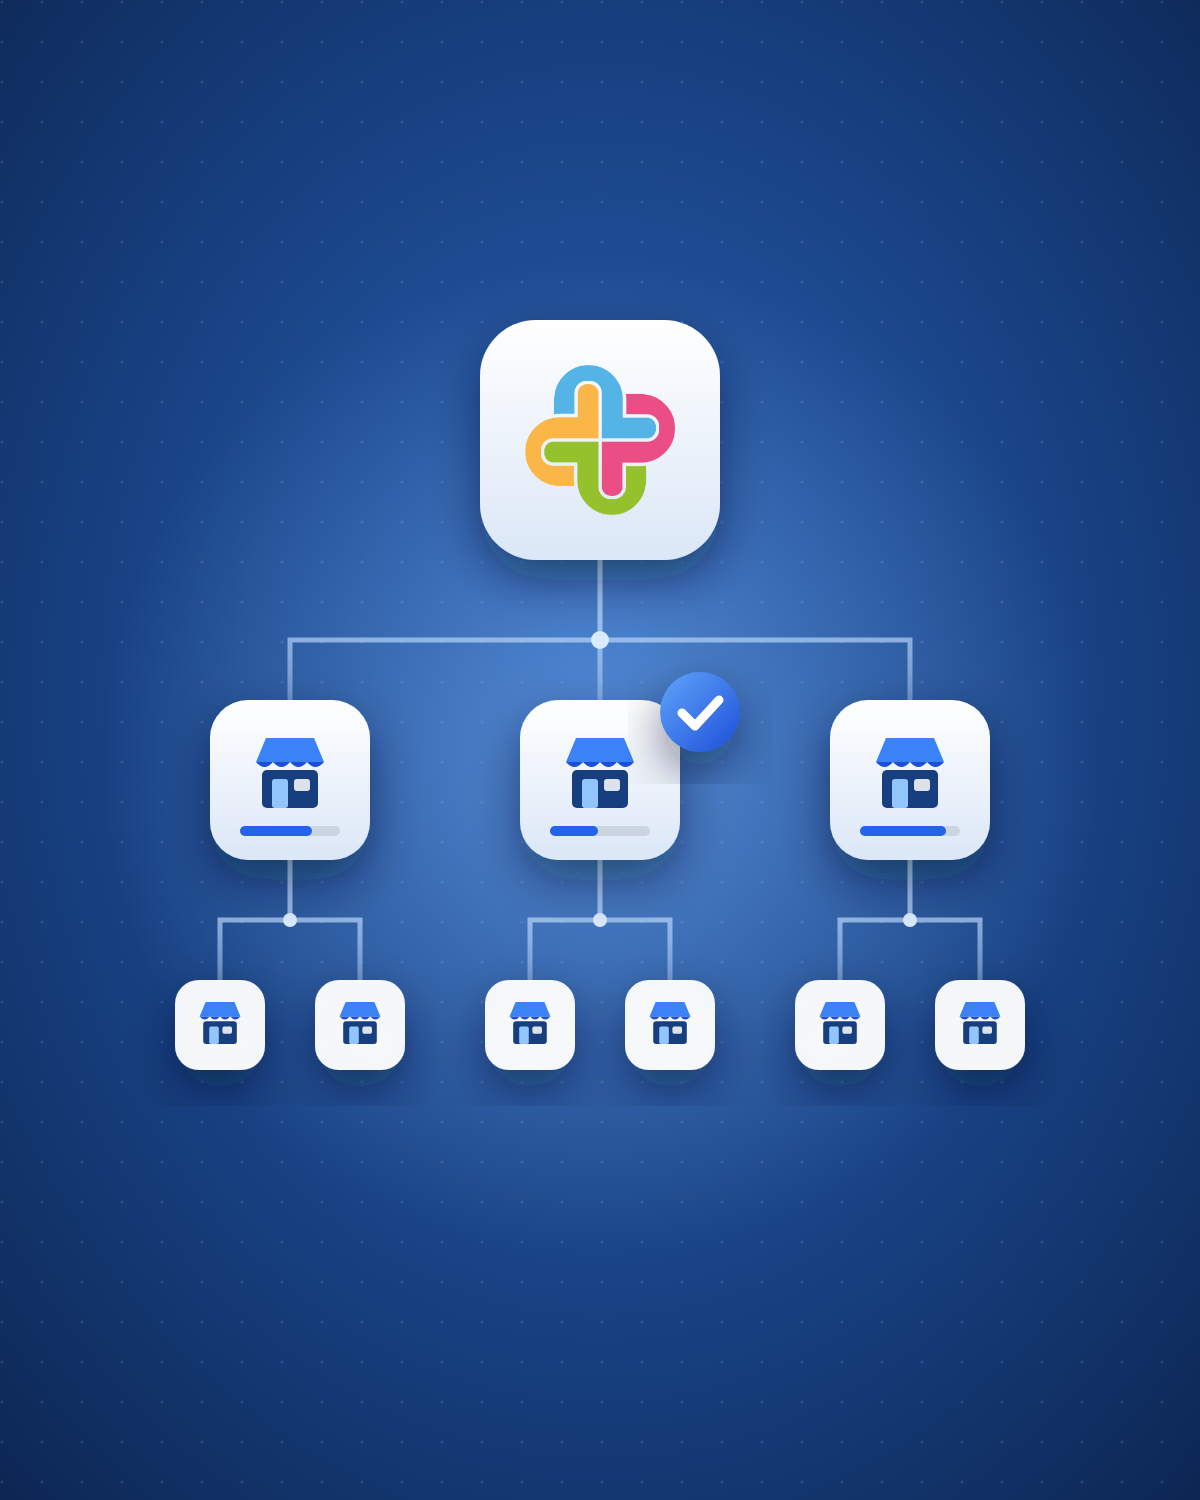
The dealer system puts limits, catalog and applications directly in the dealer channel.

Invoices and approvals live on paper

Collecting invoices, chasing buyer approvals and keying in data slows every disbursement.

How we solve it

Invoice capture, buyer approval and rule sets run digitally, with invoices submitted to DBS automatically.

No single view of limits and risk

Across distributors, dealers and sub-dealers, exposure is spread over spreadsheets and separate systems.

How we solve it

Limits are allocated down the hierarchy and monitored centrally across the whole network.

What's inside

Dealer / sub-dealer system

Hierarchy, limit allocation, catalog

Supplier Finance

Invoice capture, buyer approval, rule sets

DBS

Invoices automatically submitted to the direct debit system (DBS)

Digital financing

Individual and corporate applications, disbursement

Complementary financing system for consumer finance companies

A financing layer that complements consumer finance companies' existing systems and plugs into their dealer channel

How it works

  1. 1

    Onboard dealers

    The manufacturer or distributor brings its dealers and sub-dealers onto the platform.

  2. 2

    Set limits

    The financier assigns limits and allocates them down the dealer hierarchy.

  3. 3

    Dealer orders

    The dealer orders from the catalog and draws on its available limit.

  4. 4

    Supplier gets paid

    Financing is disbursed and the supplier receives payment for the order.

  5. 5

    Collect at maturity

    At maturity, collection runs through the direct debit system (DBS).

  6. 6

    Monitor centrally

    Limits, usage and risk are tracked across the whole network from one screen.

What you get

Dealer & sub-dealer hierarchy

Model distributors, dealers and sub-dealers with their relationships and roles.

Limit & risk management

Allocate limits down the hierarchy and track usage and exposure centrally.

Supplier finance

Capture invoices, collect buyer approval and finance them under your rule sets.

DBS integration

Invoices are submitted to the direct debit system automatically for collection at maturity.

Digital financing

Individual and corporate applications and disbursement, end to end online.

Catalog & rule sets

Dealer-channel catalog plus configurable approval and limit rules.

Value delivered

  • Brings financing to the dealer network's point of sale
  • New financing products without infrastructure investment
  • Eliminates manual invoice and approval processes

Use cases

Sub-dealer financing for a distributor

A white-goods and electronics distributor wants its hundreds of sub-dealers to buy stock on financed terms.

Outcome

Each sub-dealer orders against its own limit, the distributor gets paid, and collection runs via DBS at maturity.

Best for: financing companies, banks, distributors
Supplier finance programme

A large buyer wants its suppliers to get paid early on invoices it has already approved.

Outcome

Approved invoices are financed under agreed rule sets, easing suppliers' cash flow without paperwork.

Best for: factoring companies, banks, corporate buyers

Instalment loans at the dealer

A consumer finance company wants shoppers to apply for instalment financing digitally while still at the dealer.

Outcome

Applications and disbursement run online at the point of sale, so the dealer closes the sale on the spot.

Best for: consumer finance companies

Complementing an existing TFŞ system

A consumer finance company already runs a core lending system but lacks a dealer-channel layer.

Outcome

Paynion's complementary financing system plugs into the dealer channel and works alongside the existing setup.

Best for: consumer finance companies (TFŞ)

How to work with us

Ready infrastructure

Go live on existing infrastructure without a setup project of your own.

Configured with rule sets

Shape approval, limit and financing flows to your credit policy through rule sets.

Integration with your systems

Connect the platform to your existing core and accounting systems to keep one source of truth.

Strategic advantage

Financing institutions can offer credit across their entire dealer network without building their own infrastructure — on a ready, rule-driven platform that goes live right away.

Frequently asked questions

What does "no setup required" mean in practice?

The platform already runs; you configure your products, limits and rules on it rather than building or hosting your own software.

Who makes the credit decisions?

You do. Your credit policy and limits stay with your institution; the platform applies them through rule sets and approval flows.

Can it work alongside our existing system?

Yes. It can be integrated with your current systems, and for consumer finance companies it is designed to complement an existing setup.

How does collection work?

Invoices are submitted to the direct debit system (DBS) automatically, so collection happens at maturity without manual follow-up.

How is the platform priced?

It depends on the modules and scope you need. Talk to our team for a tailored proposal.

Let's launch your first product without touching your existing systems

Tell us which product you want to start with — we'll shape the PoC together.